Life insurance
Bem Promotora
Redesign of the Life Insurance flow on the payroll loans portal.
Year
2024
Client
Bem Promotora
Paper
Solo Product Designer
Categories
Redesign, Design Sprint, UX, usability testing, UX Writing, Artificial Intelligence

Impact
+20.6%
Goal achieved in February
The goal was to grow 15% in sales volume. The first full month with the new layout already grew 20.6% compared to 2024.
3.4x
Distance in the second semester
Average adoption rate from July to October: 6.3% in 2025 versus 1.8% in 2024, when the previous curve was already in free fall.
7 months
Consecutive over 2024
From April to October without any relapse. In the entire year, 8 out of the 10 months were above the previous year.
Increase the quality perceived by users
KR 2.2
100% of the messages linked to BemWeb standardized by the Product and UX Writing area and implemented by the Development team. ✅
Context
The old flow didn't show the agent how to sell it
The objective of the project was to redesign the Life Insurance hiring flow, focusing on improving the user experience and information transparency. This update included processes, enhanced communication, and marketing innovations, with the goal of increasing the sales volume of SIAPE Insurance by 15%.
There was no explanation of what the insurance covered, no visible benefits, and the inclusion of beneficiaries was mandatory to proceed. Added to this, the proposal entry process had bugs and inconsistencies inherited in the life insurance section.

Old flow
Images of old screens
Images of old screens
Context
The old flow didn't show the agent how to sell it
The objective of the project was to redesign the Life Insurance hiring flow, focusing on improving the user experience and information transparency. This update included processes, enhanced communication, and marketing innovations, with the goal of increasing the sales volume of SIAPE Insurance by 15%.
There was no explanation of what the insurance covered, no visible benefits, and the inclusion of beneficiaries was mandatory to proceed. Added to this, the proposal entry process had bugs and inconsistencies inherited in the life insurance section.
Restrictions
A good part of what seemed like an interface problem was actually an external rule. The PEP restriction is regulatory, not a design choice, so we couldn't simply remove the block. The partner insurance company defines the product, coverages, and values, which limits what the screen can offer. And there were legacy bugs to fix within the same effort.
The short deadline was what motivated the format: a Design Sprint (5 days), to go from hypothesis to defined flow in a few days instead of a long discovery cycle.

Discoveries
Journey mapping
The sprint storyboard started well before the interface: the customer goes to the store, the salesperson offers the products, the customer accepts the offer, and only then does the typing in BemWeb begin.
This shift changed the project's question. It ceased to be "how to make the screen clearer" and became "what is missing for the agent to offer this product with information".
Sprint storyboard
The first row is entirely prior to the system: the customer goes to the store, the salesperson offers the products, the customer accepts, and only then does the data entry begin. Only from the second row onward does BemWeb come into play, which made it clear that the sales decision happened before any screen appeared.

Search
For the new insurance feature to be opted-in, we conducted a brief survey with users
The user research on integrating the visualization and purchase decision of insurance into the loan simulation process received more than 150 responses. With 87% in favor of this change.
Make it easier for customers to visualize and make decisions about purchasing insurance by integrating it into the loan simulation process.
Decision 1
Simplified flow
Decision 1
Simplified flow
Two barriers were removed from the agent's path: the Politically Exposed Person (PEP) validation was moved to the insurer, and the registration of beneficiaries became optional. What remained ahead was the explanation of the product.
Two barriers were removed from the agent's path: the Politically Exposed Person (PEP) validation was moved to the insurer, and the registration of beneficiaries became optional. What remained ahead was the explanation of the product.
Old flow
Politically Exposed Persons could not join the insurance
The opt-in message was not clear to the operator, and the information on the screen was poorly organized
No explanation of the benefits and advantages of opting in
Mandatory inclusion of beneficiaries, with two blocks open by default
Politically Exposed Persons could not join the insurance
The opt-in message was not clear to the operator, and the information on the screen was poorly organized
No explanation of the benefits and advantages of opting in
Mandatory inclusion of beneficiaries, with two blocks open by default
PPE Notice
Accept or decline membership
Enter insurance details
Add 2 beneficiaries
New flow
PPE validation transferred to the insurer
Benefits dashboard + opt-in, split between customer and agent
Notification of insurance received, with minimum values and option to change
Mini-glossary with insurance terms at the point of use
Inclusion of beneficiary is now optional
PPE validation transferred to the insurer
Benefits dashboard + opt-in, split between customer and agent
Notification of insurance received, with minimum values and option to change
Mini-glossary with insurance terms at the point of use
Inclusion of beneficiary is now optional
PPE Warning (step removed)
Advantages + join
*Acceptance of joining comes pre-selected
Advantages + join
*Acceptance of joining comes pre-selected
Enter insurance details
Beneficiaries (optional)
Comparison between the old flow and the proposal
Comparison between the old flow and the proposal
The turnaround
The flow user is the agent
The new benefits panel has two columns, and that is what summarizes the case. A "For your client" column, with coverage, fixed premium, and waiver of health declaration. And a "For you" column, with portfolio expansion, differentiated commission, and compensation unlinked to the credit operation.
A B2B2C product does not sell itself just because the end customer understood it. It sells when whoever is at the counter knows what they are offering and why it is worth offering. The old screen did not provide either of these pieces of information.
Decision 2
Benefits dashboard with agent commission
Decision 2
Benefits dashboard with agent commission
Discarded alternative
Present only the product benefits to the end customer, treating the screen as support material for selling to the insured.
Present only the product benefits to the end customer, treating the screen as support material for selling to the insured.
Chosen path
Split the dashboard into "For your client" and "For you", displaying commission and compensation next to the coverage.
Split the dashboard into "For your client" and "For you", displaying commission and compensation next to the coverage.

Give the agent the talking point and the incentive on the same screen, at the exact moment they decide whether or not to offer it.
Give the agent the talking point and the incentive on the same screen, at the exact moment they decide whether or not to offer it.
Improvements
Other implemented ideas
Each improvement was born from a different question about the same flow. Making beneficiaries mandatory only became a problem when we separated what actually blocked the contracting process from what only seemed to block it.
The mini-glossary came from the perception that the friction was in the vocabulary, not in the task, and therefore the explanation was brought right to the point of use.
On the other hand, the message repository was the decision to treat communication as a system: instead of correcting text by text, we mapped everything at once and classified it by technical responsibility, which exposed rules that no longer applied.
Decision 3
Beneficiary is now optional
Decision 3
Beneficiary is now optional
Discarded alternative
Keep the required fields and reorganize them, reducing the typing effort for both beneficiary blocks.
Keep the required fields and reorganize them, reducing the typing effort for both beneficiary blocks.
Chosen path
Make the step optional, with the "Proceed without identifying" action visible next to confirm. Thus, not blocking the hiring process.
Make the step optional, with the "Proceed without identifying" action visible next to confirm. Thus, not blocking the hiring process.

Objective of the change: to reduce steps and make the hiring decision clearer, without requiring added beneficiaries.
Objective of the change: to reduce steps and make the hiring decision clearer, without requiring added beneficiaries.
Decision 4
Miniglossary of pay-as-you-go insurance terms
Decision 4
Miniglossary of pay-as-you-go insurance terms
Discarded alternative
Present only the product benefits to the end customer, treating the screen as support material for selling to the insured.
Present only the product benefits to the end customer, treating the screen as support material for selling to the insured.
Chosen path
Split the dashboard into "For your client" and "For you", displaying commission and compensation next to the coverage.
Split the dashboard into "For your client" and "For you", displaying commission and compensation next to the coverage.

Give the agent the talking point and the incentive on the same screen, at the exact moment they decide whether or not to offer it.
Give the agent the talking point and the incentive on the same screen, at the exact moment they decide whether or not to offer it.
Decision 5
Using AI to create standardized messages in the Life Insurance flow
Decision 5
Using AI to create standardized messages in the Life Insurance flow
Discarded alternative
Fix the confusing messages as they appeared in the tests, one by one, within the insurance flow itself.
Fix the confusing messages as they appeared in the tests, one by one, within the insurance flow itself.
Chosen path
Assemble a repository with all insurance messages revised and classified by FrontEnd, BackEnd, and messages to be removed. To standardize the messages and maintain consistency, I used ChatGPT with UX Writing guidelines and the brand voice as a reference, reviewing and validating each message.
Assemble a repository with all insurance messages revised and classified by FrontEnd, BackEnd, and messages to be removed. To standardize the messages and maintain consistency, I used ChatGPT with UX Writing guidelines and the brand voice as a reference, reviewing and validating each message.
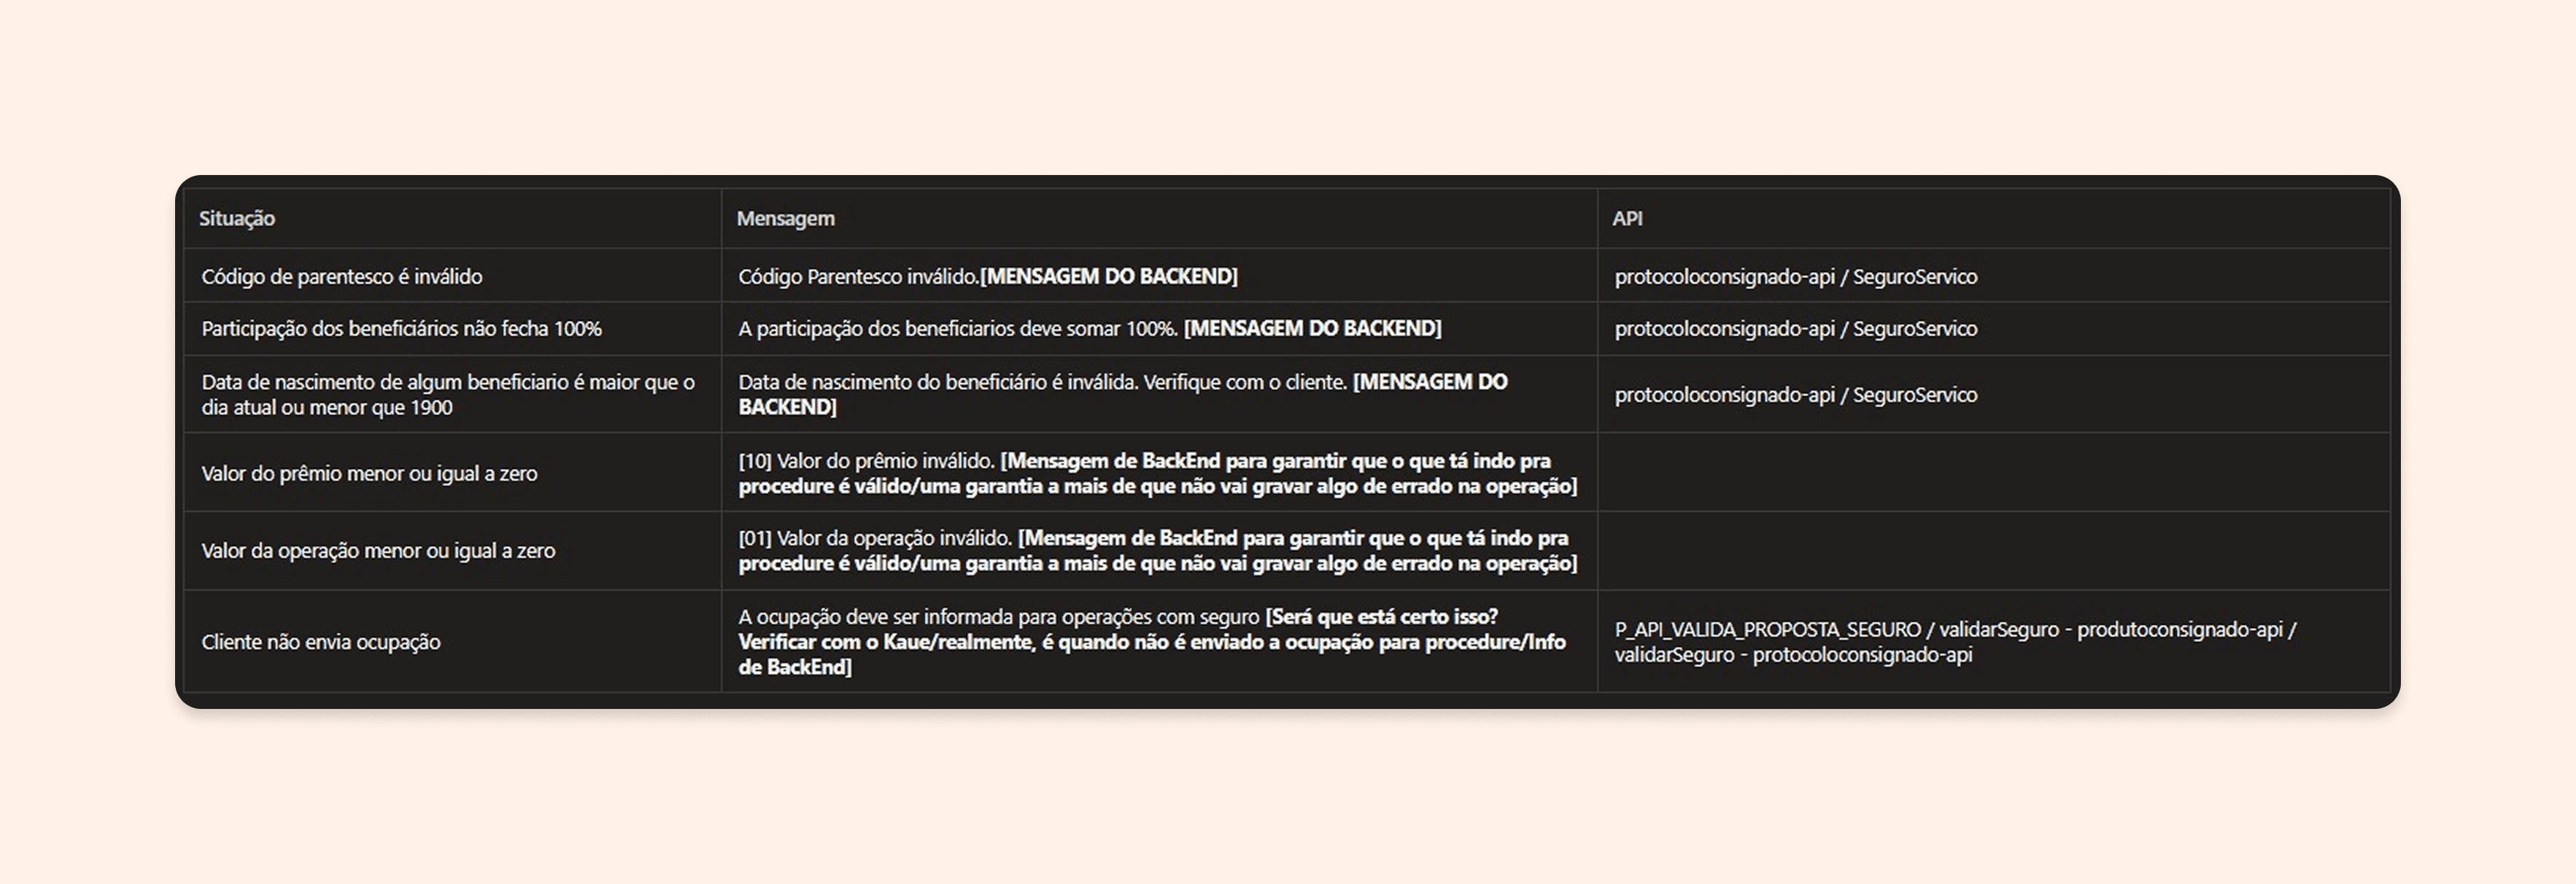
Message catalog: Confirmations with undo actions and alerts that state the limit instead of just pointing out the error.
Message catalog: Confirmations with undo actions and alerts that state the limit instead of just pointing out the error.
Validation and testing
Tested with those who sell
The new flow was validated in a usability test using the Mirror Room setup, which allows the team to monitor the user's reactions in real-time without interfering with the session, with 5 store users.
The sessions measured two different things. The first was whether the flow worked, where 4 users completed the task and 1 experienced difficulty with the new "Proceed without beneficiaries" button. The second was whether the agent approved of the change, which was the most critical point, and all approved because it would make the process faster.
The observed difficulties were incorporated into the journey prior to delivery.
The new flow was validated in a usability test with the Mirror Room type, which allows the team to follow the user's reactions in real-time without interfering with the session, with 5 store users.
The sessions measured two different things. The first was whether the flow worked: 4 users completed the task and 1 had difficulty with the new Proceed without beneficiaries button.
The observed difficulties were incorporated into the journey before delivery.
The new flow was validated in a usability test using the Mirror Room setup, which allows the team to monitor the user's reactions in real-time without interfering with the session, with 5 store users.
The sessions measured two different things. The first was whether the flow worked, where 4 users completed the task and 1 experienced difficulty with the new "Proceed without beneficiaries" button. The second was whether the agent approved of the change, which was the most critical point, and all approved because it would make the process faster.
The observed difficulties were incorporated into the journey prior to delivery.
Quote
“Keeping the listening cycle running every six months is what allowed us to treat NPS as a symptom.”
Project Owner, during usability testing

Results
A number that did not explain itself
April draws more attention, but it is the least conclusive month: the peak coincided with the increase in the SIAPE margin and the release of the feature to more Corbans. February is the clean data. Only the new layout changed, only in the proprietary network, and no other factor entered the period. It is the closest to a controlled experiment that this project had.
That is why the graph should be read in three stages: the isolated effect of the launch, the peak with external factors, and the plateau that remained afterward.
+20.6%
Goal achieved in February
The goal was to grow 15% in sales volume. The first full month with the new layout already grew 20.6% compared to 2024.
+20.6%
Goal achieved in February
The goal was to grow 15% in sales volume. The first full month with the new layout already grew 20.6% compared to 2024.
3.4x
Distance in the second semester
Average adoption rate from July to October: 6.3% in 2025 versus 1.8% in 2024, when the previous curve was already in free fall.
3.4x
Distance in the second semester
Average adoption rate from July to October: 6.3% in 2025 versus 1.8% in 2024, when the previous curve was already in free fall.
7 months
Consecutive over 2024
From April to October without any relapse. In the entire year, 8 out of the 10 months were above the previous year.
7 months
Consecutive over 2024
From April to October without any relapse. In the entire year, 8 out of the 10 months were above the previous year.
Increase the quality perceived by users
KR 2.2
100% of the messages linked to BemWeb standardized by the Product and UX Writing area and implemented by the Development team. ✅
Increase the quality perceived by users
KR 2.2
100% of the messages linked to BemWeb standardized by the Product and UX Writing area and implemented by the Development team. ✅
+20.6%
Goal achieved in February
The goal was to grow 15% in sales volume. The first full month with the new layout already grew 20.6% compared to 2024.
3.4x
Distance in the second semester
Average adoption rate from July to October: 6.3% in 2025 versus 1.8% in 2024, when the previous curve was already in free fall.
7 months
Consecutive over 2024
From April to October without any relapse. In the entire year, 8 out of the 10 months were above the previous year.
Increase the quality perceived by users
KR 2.2
100% of the messages linked to BemWeb standardized by the Product and UX Writing area and implemented by the Development team. ✅
In a direct comparison with 2024, the evolution went from −45.8% in January to +20.6% in February, and reached +306.9% in September. The relative gain grows throughout the year because the 2024 base continued to fall while the 2025 base stabilized.
In a direct comparison with 2024, the evolution went from −45.8% in January to +20.6% in February, and reached +306.9% in September. The relative gain grows throughout the year because the 2024 base continued to fall while the 2025 base stabilized.
Learnies
In B2B2C, the operator is the user
The screen wasn't selling because the agent had neither an argument nor a visible incentive. No improvement aimed at the end customer would have solved this.
Not every barrier is solved in the interface
The PEP lock was not rewritten, it was relocated. Asking whose rule it is usually yields more results than asking how to explain it better.
Isolate the effect of the context
February is a smaller number than April, but it is the defensible number. Addressing the external factor before they ask is worth more than showing off the peak.
Learn more

